Home › Coverages › Commercial Refrigeration Contractor Insurance
Insurance for commercial refrigeration contractors
Refrigeration contractor insurance protects the shop that keeps walk-in coolers, reach-ins, ice machines and display cases running for restaurants, grocers and convenience stores. The core policies look like any HVAC shop's, but the questions that matter most are how a food-loss claim would be handled after a repair fails, how your refrigerant work is documented and who answers the phone at 2 a.m.
- Since 2003
- 12+ A-rated carriers
- 28 states
- Independent agents
Start your HVAC insurance quote
Takes about two minutes. A licensed agent follows up.
Licensed in 28 states · NPN 7642818 · Since 2003
Where refrigeration contractor insurance gets tested
Commercial refrigeration fails differently from comfort cooling. When a rooftop unit quits, a building gets warm. When a walk-in quits, a customer's inventory starts losing value by the hour, and the first call after the repair is often about money. Here's where the claims tend to start:
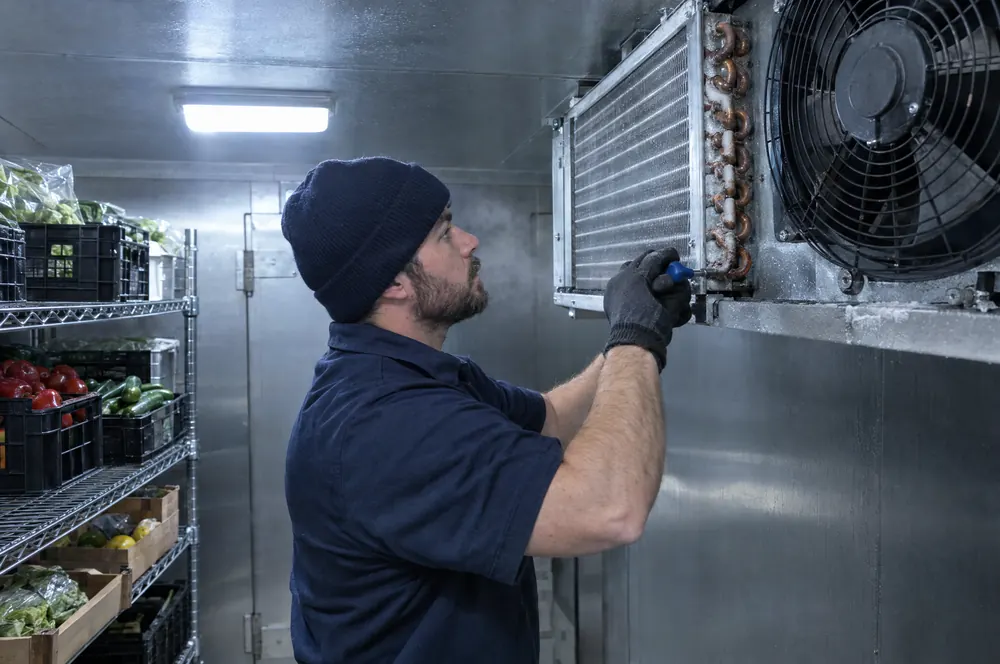
- A repair that doesn't hold. A compressor, a valve or a defrost control you replaced fails overnight, and the restaurant or store wants you to pay for the product it threw out.
- Water where it shouldn't be. An ice machine's drain line slips off its fitting and soaks a basement storeroom, or a walk-in's defrost drain freezes and backs up under the floor panels into the dining room.
- A torch near foam panels. Brazing a line set inside an equipment room lined with insulated panels can start a fire that's hard to put out.
- The customer's equipment in your hands. A condensing unit's compressor is damaged while your tech is working on it. That's a common gap in liability coverage, covered below.
- Refrigerant in a small room. A recovery hose fails in a cramped back room and an employee of the store gets dizzy. Refrigerant releases are a pollution question as much as a liability one.
- Late nights. One tech, driving to a grocery store at 2 a.m. with cylinders in the van, working alone in a cold box. That's a workers' comp and auto exposure as much as a liability one.
This page is about commercial refrigeration for food service and retail. Industrial ammonia systems are a different class that underwriters review separately.
The refrigeration contractor's coverage stack
Underwriters often rate commercial refrigeration under its own liability class, separate from heating and air conditioning. In NCCI states, the main workers' comp code for HVAC also names refrigeration in its title.
General liability
Injury and property damage claims from your work, including completed operations after a repair is closed out. HVAC general liability
Workers' comp
For the techs lifting condensing units, working in cold boxes and handling refrigerant. Workers' comp for HVAC and refrigeration
Commercial auto
Service vans carrying cylinders, recovery machines and parts to after-hours calls. Commercial auto for HVAC
Tools and equipment
Recovery machines, vacuum pumps, micron gauges, leak detectors and refrigerant scales. HVAC tools insurance
What refrigeration work often adds
Contractors pollution liability
For refrigerant releases and other contamination claims a liability policy may exclude. Pollution liability for HVAC
Installation floater
New condensing units, evaporators, cases and controls until the store accepts the job. Installation floater
Umbrella
Higher limits for grocery chains and restaurant groups whose contracts ask for more than $1 million. Umbrella for HVAC contractors
Business owner's policy
A package for your shop and parts stock, if you qualify. One published BOP program lists commercial refrigeration installation and service among its eligible classes. BOP for HVAC shops
What grocers, restaurant groups and property owners will ask for
Larger food-service and retail accounts usually send a vendor packet before the first service call. Expect to see:
- A certificate of insurance naming the customer as additional insured, often with a waiver of subrogation, at limits that may push you toward an umbrella.
- A service agreement with response-time commitments, spoilage language and an indemnity clause. Read all three before you sign.
- Proof of EPA 608 certification for techs who open systems, and charging and leak-repair records for appliances covered by the leak rules.
- The right state license. Several states license refrigeration separately from comfort HVAC.
Those license differences are real. Texas air conditioning and refrigeration contractor licenses carry endorsements, and commercial refrigeration and process cooling or heating is its own endorsement (see HVAC contractor insurance in Texas). Ohio issues a refrigeration contractor license separate from the HVAC license, and both carry the state's $500,000 liability floor (see HVAC contractor insurance in Ohio). California has its own C-38 refrigeration classification, and its comp-exemption rules differ from the C-20 HVAC class (see HVAC contractor insurance in California). Michigan treats refrigeration as one of ten classifications on a single mechanical contractor license.
Growing a refrigeration service business
Refrigeration shops tend to grow account by account. Each new kind of customer changes what you need underneath.
- First restaurant group or c-store chain. Expect a vendor packet, higher limits and additional insured requests. Price the umbrella into the contract.
- First 24-hour coverage promise. Staff for it, and write the response terms carefully. A missed response time is usually a contract issue, not an insured one.
- Moving from repair into installs. New condensing units and cases bring an installation floater and a larger completed-operations exposure.
- Adding techs. Keep helpers supervised until they're certified, and keep payroll in the right class codes for audit.
- A shop with parts stock. A business owner's policy may fit, if your class and size qualify.
Refrigeration contractor insurance questions
Does insurance cover food spoilage if my repair fails?
What insurance does a refrigeration contractor need?
Do I need pollution insurance for refrigerant leaks?
Is the workers' comp code for refrigeration different from HVAC?
Will insurance pay an EPA fine for a refrigerant violation?
Related pages
Ready to see what you'd pay?
Independent agents, 12+ A-rated carriers, and a licensed agent back to you within one business day.